美国国税局(IRS)公布2025年最新税收调整方案 IRS releases tax inflation adjustments for tax year 2025
华盛顿——美国国税局(IRS)近日宣布了2025纳税年度的年度通胀调整内容。这些调整涉及60多项税收规定的变更,影响纳税人从2026年报税季开始提交的申报。以下是2025年最受关注的税收调整:
主要调整
标准扣除额
单身纳税人和分开申报的已婚人士:标准扣除额提高到15,000美元(比2024年增加400美元)。
联合申报的已婚夫妇:标准扣除额提高到30,000美元(比2024年增加800美元)。
户主:标准扣除额提高到22,500美元(比2024年增加600美元)。
边际税率
37%税率:个人收入超过626,350美元(已婚联合申报超过751,600美元)。
35%税率:个人收入超过250,525美元(已婚联合申报超过501,050美元)。
32%税率:个人收入超过197,300美元(已婚联合申报超过394,600美元)。
24%税率:个人收入超过103,350美元(已婚联合申报超过206,700美元)。
22%税率:个人收入超过48,475美元(已婚联合申报超过96,950美元)。
12%税率:个人收入超过11,925美元(已婚联合申报超过23,850美元)。
10%税率:个人收入11,925美元及以下(已婚联合申报23,850美元及以下)。
其他显著变化
替代性最低税(AMT)豁免额
单身纳税人:豁免额提高至88,100美元(分开申报的已婚人士为68,650美元),逐步减少起点为626,350美元。
已婚联合申报:豁免额提高至137,000美元,逐步减少起点为1,252,700美元。
所得税抵免(EITC)
有三名或以上合格子女的纳税人,2025年最高所得税抵免金额为8,046美元(2024年为7,830美元)。
合格交通福利
月度限额提高到325美元(2024年为315美元)。
健康灵活支出账户(FSA)
员工薪资减少用于健康FSA的限额增加到3,300美元(2024年为3,200美元)。未使用金额的最大结转金额提高到660美元(2024年为640美元)。
医疗储蓄账户(MSA)
单人计划的年度免赔额范围:$2,850-$4,300,自付费用限额提高至**$5,700**。
家庭计划的年度免赔额范围:$5,700-$8,550,自付费用限额提高至**$10,500**。
海外收入排除
海外收入排除额提高到130,000美元(2024年为126,500美元)。
遗产税排除额
2025年遗产税基本排除额提高到13,990,000美元(2024年为13,610,000美元)。
年度赠与税豁免额
2025年增加到19,000美元(2024年为18,000美元)。
收养税收抵免
特殊需要儿童收养的最高抵免额增加到17,280美元(2024年为16,810美元)。
未调整项目
根据法律规定,以下项目保持不变:
个人豁免额:2025年仍为0,与2024年一致。
逐项扣除额限制:2025年仍无逐项扣除限制。
IR-2024-273, Oct. 22, 2024
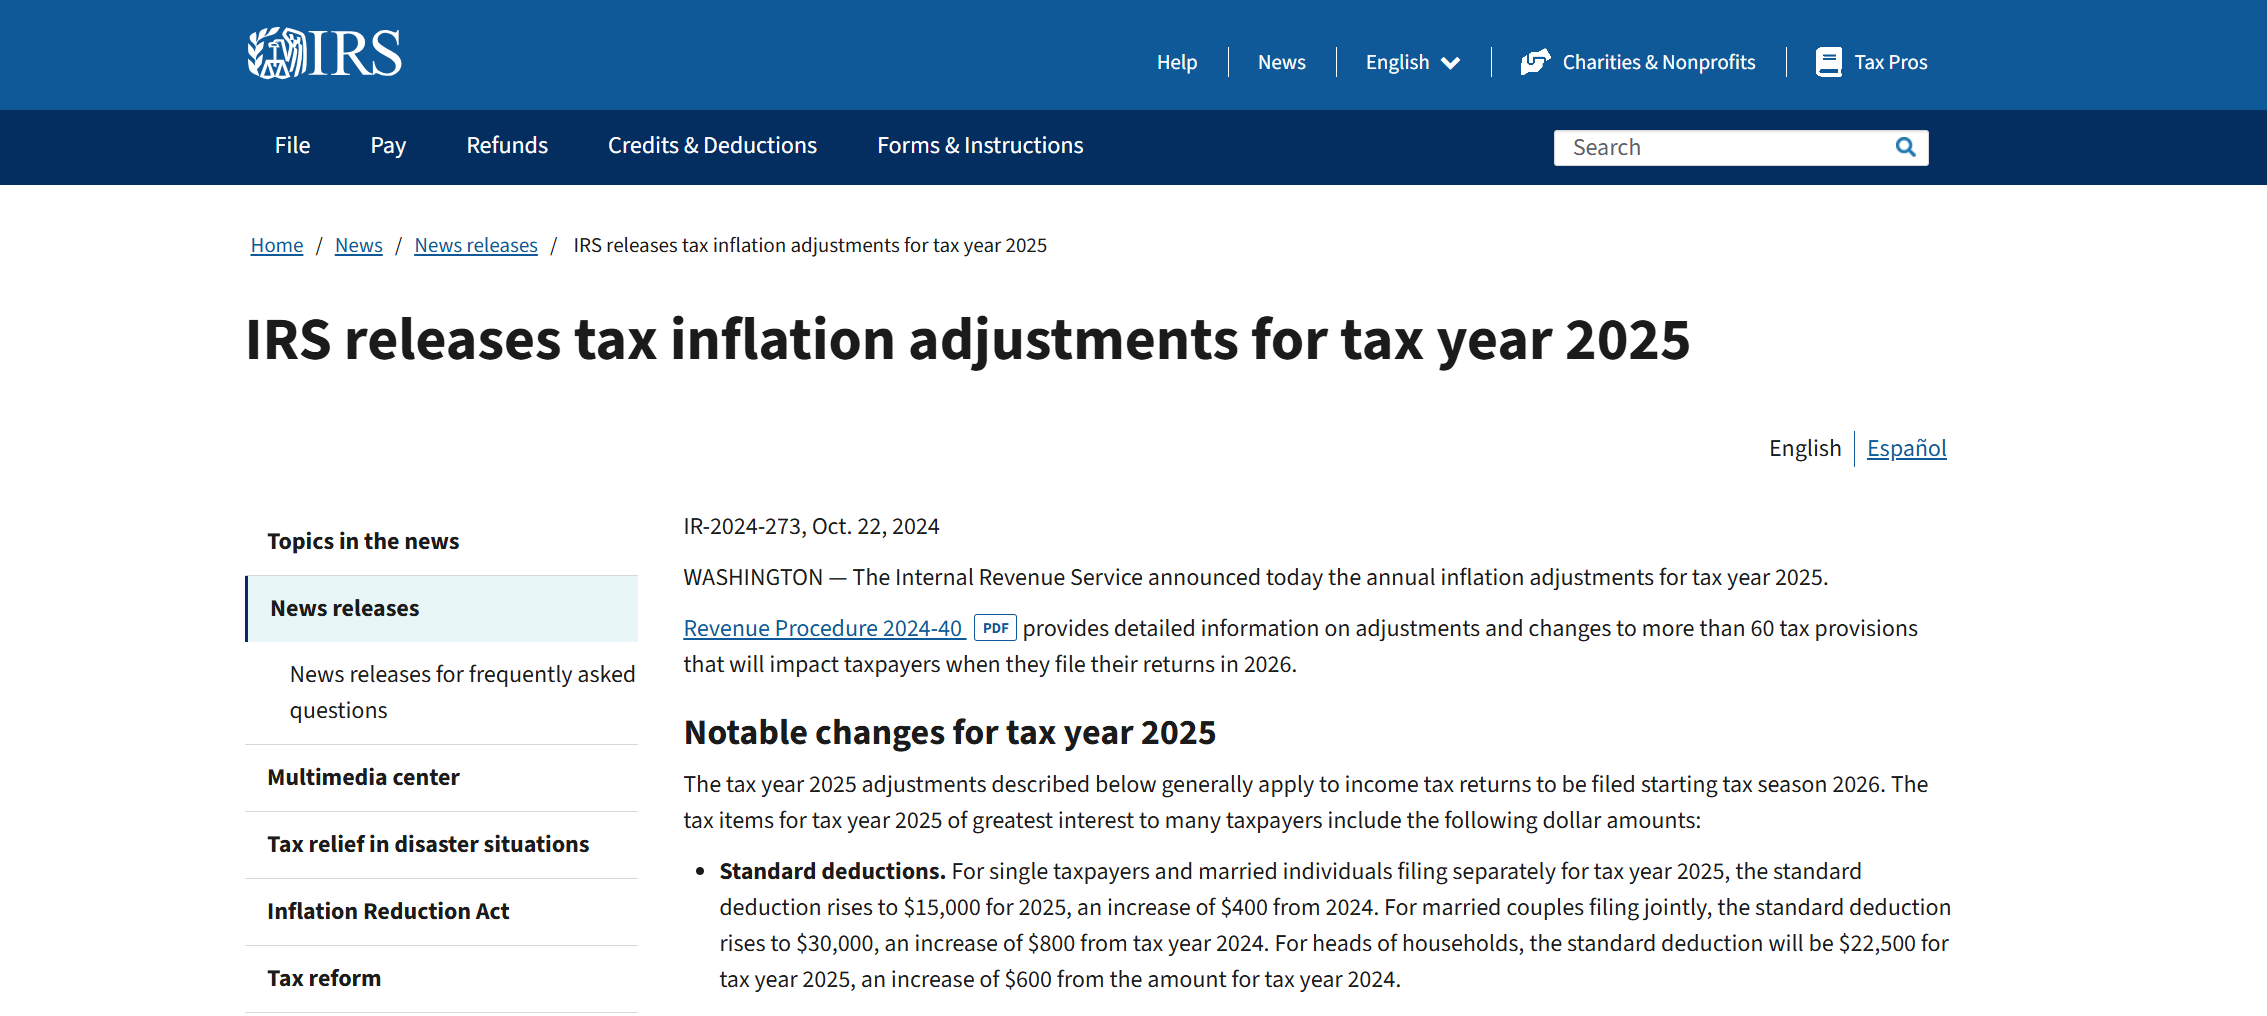
WASHINGTON — The Internal Revenue Service announced today the annual inflation adjustments for tax year 2025.
Revenue Procedure 2024-40 PDF provides detailed information on adjustments and changes to more than 60 tax provisions that will impact taxpayers when they file their returns in 2026.
Notable changes for tax year 2025
The tax year 2025 adjustments described below generally apply to income tax returns to be filed starting tax season 2026. The tax items for tax year 2025 of greatest interest to many taxpayers include the following dollar amounts:
Standard deductions. For single taxpayers and married individuals filing separately for tax year 2025, the standard deduction rises to $15,000 for 2025, an increase of $400 from 2024. For married couples filing jointly, the standard deduction rises to $30,000, an increase of $800 from tax year 2024. For heads of households, the standard deduction will be $22,500 for tax year 2025, an increase of $600 from the amount for tax year 2024.
Marginal rates. For tax year 2025, the top tax rate remains 37% for individual single taxpayers with incomes greater than $626,350 ($751,600 for married couples filing jointly). The other rates are:
35% for incomes over $250,525 ($501,050 for married couples filing jointly).
32% for incomes over $197,300 ($394,600 for married couples filing jointly).
24% for incomes over $103,350 ($206,700 for married couples filing jointly).
22% for incomes over $48,475 ($96,950 for married couples filing jointly).
12% for incomes over $11,925 ($23,850 for married couples filing jointly).
10% for incomes $11,925 or less ($23,850 or less for married couples filing jointly).
Alternative minimum tax exemption amounts. For tax year 2025, the exemption amount for unmarried individuals increases to $88,100 ($68,650 for married individuals filing separately) and begins to phase out at $626,350. For married couples filing jointly, the exemption amount increases to $137,000 and begins to phase out at $1,252,700.
Earned income tax credits. For qualifying taxpayers who have three or more qualifying children, the tax year 2025 maximum Earned Income Tax Credit amount is $8,046, an increase from $7,830 for tax year 2024. The revenue procedure contains a table providing maximum EITC amount for other categories, income thresholds and phase-outs.
Qualified transportation fringe benefit. For tax year 2025, the monthly limitation for the qualified transportation fringe benefit and the monthly limitation for qualified parking rises to $325, increasing from $315 in tax year 2024.
Health flexible spending cafeteria plans. For the taxable years beginning in 2025, the dollar limitation for employee salary reductions for contributions to health flexible spending arrangements rises to $3,300, increasing from $3,200 in tax year 2024. For cafeteria plans that permit the carryover of unused amounts, the maximum carryover amount rises to $660, increasing from $640 in tax year 2024.
Medical savings accounts. For tax year 2025, participants who have self-only coverage the plan must have an annual deductible that is not less than $2,850 (a $50 increase from the previous tax year), but not more than $4,300 (an increase of $150 from the previous tax year).
The maximum out-of-pocket expense amount rises to $5,700, increasing from $5,550 in tax year 2024.
For family coverage in tax year 2025, the annual deductible is not less than $5,700, increasing from $5,550 in tax year 2024; however, the deductible cannot be more than $8,550, an increase of $200 versus the limit for tax year 2024. For family coverage, the out-of-pocket expense limit is $10,500 for tax year 2025, rising from $10,200 in tax year 2024.
Foreign earned income exclusion. For tax year 2025, the foreign earned income exclusion increases to $130,000, from $126,500 in tax year 2024.
Estate tax credits. Estates of decedents who die during 2025 have a basic exclusion amount of $13,990,000, increased from $13,610,000 for estates of decedents who died in 2024.
Annual exclusion for gifts increases to $19,000 for calendar year 2025, rising from $18,000 for calendar year 2024.
Adoption credits. For tax year 2025, the maximum credit allowed for an adoption of a child with special needs is the amount of qualified adoption expenses up to $17,280, increased from $16,810 for tax year 2024.
Unchanged for tax year 2025
By statute, certain items that were indexed for inflation in the past are currently not adjusted.
Personal exemptions for tax year 2025 remain at 0, as in tax year 2024. The elimination of the personal exemption was a provision in the Tax Cuts and Jobs Act of 2017.
Itemized deductions. There is no limitation on itemized deductions for tax year 2025, as in tax year 2024 and preceding, to tax year 2018. The limitation on itemized deductions was eliminated by the Tax Cuts and Jobs Act of 2017.
Lifetime learning credits. The modified adjusted gross income amount used by taxpayers to determine the reduction in the Lifetime Learning Credit provided in Sec. 25A(d)(1) of the Internal Revenue Code is not adjusted for inflation for taxable years beginning after Dec. 31, 2020. The Lifetime Learning Credit is phased out for taxpayers with modified adjusted gross income in excess of $80,000 ($160,000 for joint returns).

 标准扣除额
 标准扣除额




 扫一扫
添加客服


